Key takeaways
- Sales tax you collect isn't an expense, and it isn't revenue. It's money you hold for the state, in Sales Tax Payable. In our example, a coffee shop takes in $10,800 for $10,000 of sales and owes $800.
- Paying the state isn't an expense either. The $760 payment ($800 collected, less $40 refunded) clears the liability. If the account isn't at zero after filing, something was coded wrong: check the payment and the deposits first.
- Sales tax you pay on purchases is part of what you bought: $216 of supplies expense, $1,080 of inventory, a $2,592 espresso machine. There's no separate "sales tax expense," and the tax can push an item over the $2,500 de minimis limit.
- The exception: a tax that's legally on the seller (Hawaii, New Mexico, Arizona, and Washington's B&O tax). There, the IRS has you include what you charged in gross receipts and deduct the tax on Schedule C line 23. Profit comes out the same.
- No tax charged on a taxable purchase? The business may owe use tax, recorded as part of the item's cost. The same goes for stock bought tax-free for resale and then used in the business.
Is sales tax an expense?
In short: Usually not on a line of its own (the exception, a tax on the seller, is below). Sales tax you collect from customers is a liability you owe the state. Sales tax you pay on purchases is part of what you bought: expensed with supplies, held in inventory, or added to the cost of equipment.
Why two answers? "Sales tax" shows up in two places in your books, and they're treated in opposite ways:
- Tax you collect on your sales belongs to the state from the moment you collect it. You hold it until the return is due, so it's a liability. Sending it to the state pays that liability off.
- Tax you pay when you buy something is part of what the item cost. Supplies with tax are a supplies expense, inventory with tax is inventory, and equipment with tax is equipment.
Here's the first case with numbers. A sample coffee shop sells $100 of coffee beans and charges 8% sales tax:
“State and local sales taxes imposed on the buyer, which you were required to collect and pay over to state or local governments, are not income.”
The words "imposed on the buyer" carry the exception. In a few states the tax is legally on the seller. There, what you collect is gross receipts, and the tax is a deduction (below).
Which case are you in?
In short: One question decides it: did the business collect this tax from a customer, or pay it on something it bought?
Did you collect this tax from a customer, or pay it on something you bought?
AYou collected it
- Most states: the tax is on the buyerOwed→ A liability, not revenue or an expenseSales Tax Payable. Leave it out of gross receipts.
- The tax is legally on you, the seller (Hawaii, New Mexico, Arizona, Washington's B&O tax)Income or cost→ Include it in gross receipts, then deduct itSchedule C line 1, then line 23
- The state lets you keep part of itIncome or cost→ The part you keep is incomeSchedule C line 6
- A marketplace collected it and pays the stateNot yours→ Not your liabilityLeave it out of Sales Tax Payable and of gross receipts
BYou paid it
- Supplies or a serviceIncome or cost→ Part of that expense$200 of supplies + $16 tax = $216 supplies expense
- Inventory you'll resellIncome or cost→ Part of the inventory's costExpensed through cost of goods sold when it sells. A resale certificate avoids the tax.
- Equipment or another assetIncome or cost→ Added to the asset's basis$2,400 + $192 tax = $2,592, over the $2,500 de minimis limit
- The vendor charged no tax, or you used stock bought for resaleOwed→ You may owe use taxPart of the item's cost, with Use Tax Payable until you file
Our example business, Harbor Coffee Co, is that sample coffee shop. The rest of the article follows it through one month, March, at an 8% rate. Its bookkeeper is Jordan Miles of Northline Bookkeeping. The people, the business, the rate, and the amounts are made up to show the entries. Your state and local rates will differ.
How do you record sales tax you collect?
In short: Credit it to Sales Tax Payable when you make the sale, and debit Sales Tax Payable when you pay the state. A tax imposed on the buyer never passes through the profit and loss statement. Only a discount the state lets you keep does.
“Don't deduct state and local sales taxes imposed on the buyer that you must collect and pay over to the state or local government. Don't include these taxes in gross receipts or sales.”
Record the sale
| Account | Debit | Credit |
|---|---|---|
| Cash or accounts receivable | $10,800 | |
| Sales revenue | $10,000 | |
| Sales Tax Payable | $800 |
$10,000 × 8% = $800. Revenue is $10,000, not the $10,800 that reached the bank.
Record a refund
| Account | Debit | Credit |
|---|---|---|
| Sales returns and allowances | $500 | |
| Sales Tax Payable | $40 | |
| Cash | $540 |
$500 × 8% = $40, so the liability drops from $800 to $760.
Pay the state
| Account | Debit | Credit |
|---|---|---|
| Sales Tax Payable | $760 | |
| Cash | $760 |
No expense account. The payment only clears the liability.
Sales Tax Payable, March
Debit (−)
Credit (+)
Recording the payment in QuickBooks Online
A payment to the state that arrives through the bank feed can get categorized as an expense by mistake. In QuickBooks Online, record it in the sales tax center instead.
Intuit's help page gives the path: All apps, then Sales Tax, then Overview. "From the Sales Tax Owed list, select the tax agency you're recording the payment for, then select Record Tax Payment."
Pick the bank account, the payment date, and the amount, then select Record Tax Payment. Back in the bank feed, match the downloaded line to that payment instead of adding a new expense. Otherwise the same $760 goes into the books a second time, as an expense.
What if the amount paid differs from what QuickBooks shows as owed? Select Make Adjustment when you record the payment. Intuit's rule for the adjustment account: "Don't select the sales tax Payable account."
A credit or discount goes to "an income account, such as Other Income." A "fine, penalty, or interest due" goes to an expense account. A rounding difference goes to income if negative and to expense if positive.
That matches the discount entry below: the $3.80 Harbor Coffee Co keeps is other income. A penalty is a separate expense in the books, and it isn't deductible (see the Schedule C table).
Other software: the test is the same in any program. After the payment posts, Sales Tax Payable should drop by the amount on the return, and no expense account should move. If one did, recode the payment.
Tie the account to the return every month
Before you file, compare the Sales Tax Payable balance with what the return says is owed. When they differ, match the difference to one entry. A difference equal to 8% of a deposit points at that deposit. One equal to a payment points at that payment.
Say one day's card deposit of $1,080 ($1,000 of sales plus $80 of tax) came in through the bank feed and was categorized as sales:
| Tax owed on the return: $800 charged − $40 refunded | $760 |
| Sales Tax Payable in the books: $800 − $80 never recorded | $720 |
| Less the refund | −$40 |
| Balance in the books | $680 |
| Difference: $760 − $680 | $80 |
$80 is 8% of $1,000, the tax inside that deposit. Move it from sales revenue to Sales Tax Payable, and revenue drops back to $10,000. If the difference equals a payment, check whether that payment was coded to an expense.
Our sales tax reconciliation tool runs this check from the trial balance and the month's sales reports. Here it is with Harbor Coffee Co's March numbers:
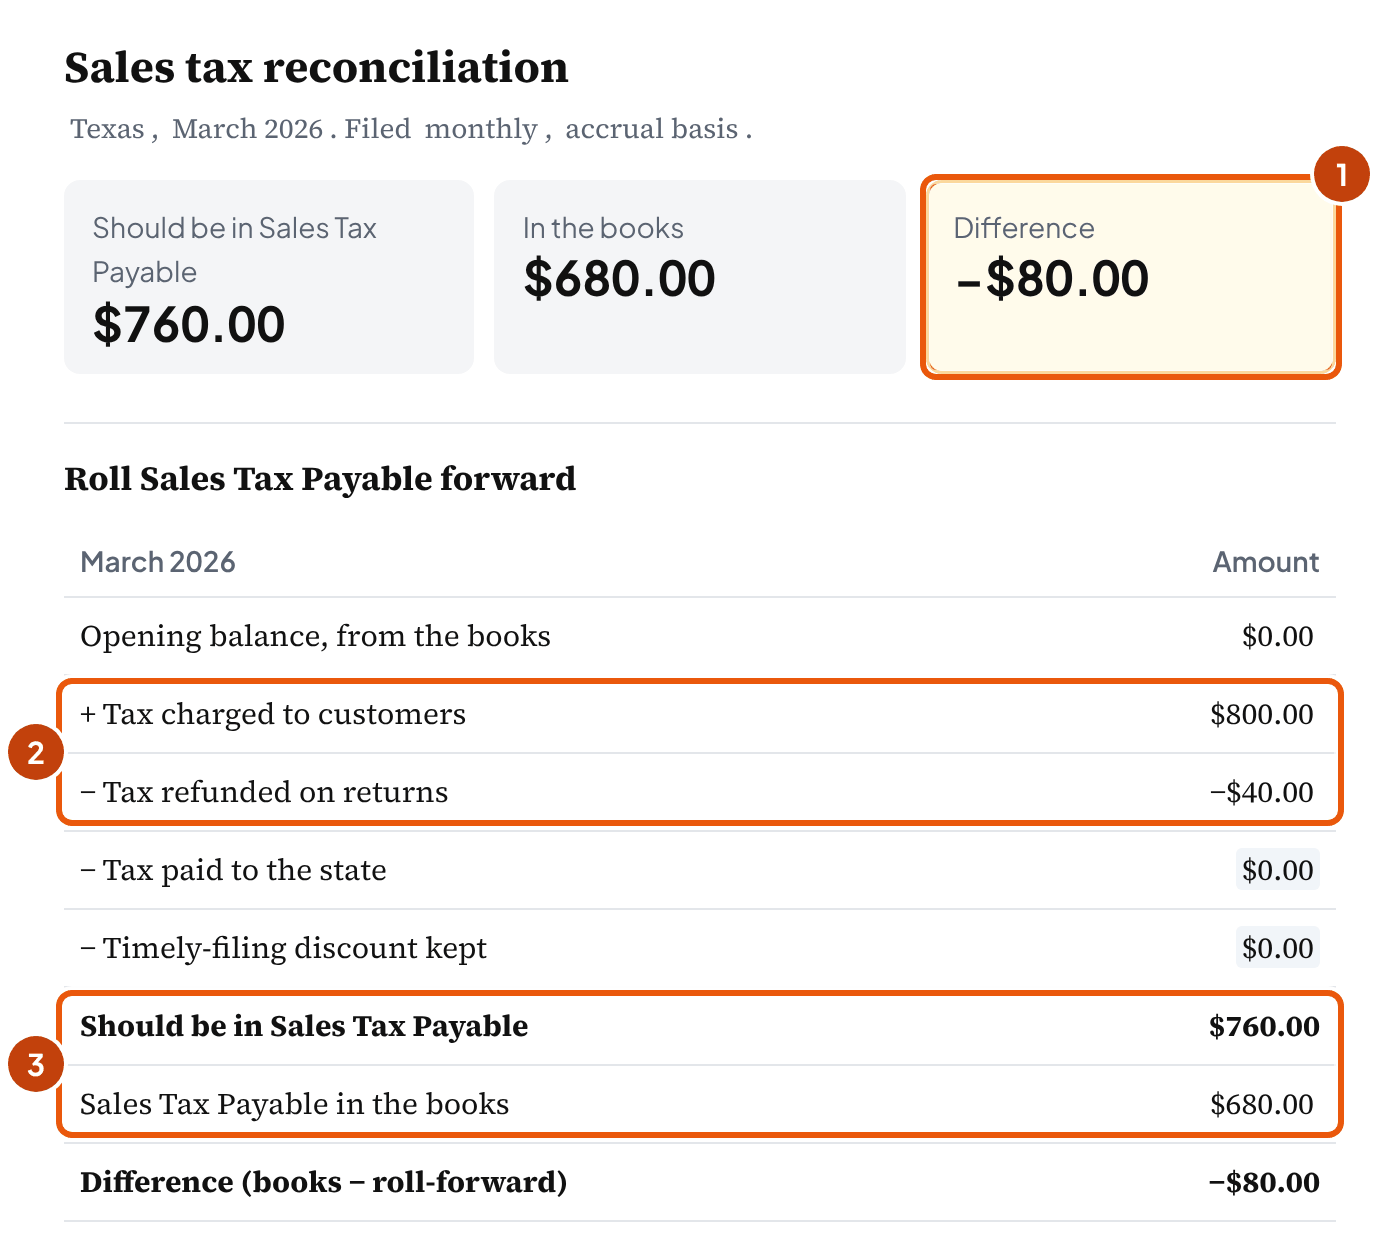
To run it yourself, open the tool with Harbor Coffee Co's March numbers. It opens with Texas selected, because the tool needs a state; no discount comes into it, since nothing had been paid yet. Then change any amount to your client's.
The tool also lists causes to check for a difference. It applies the state's discount and marketplace rules where it has them, so the same check works for a client in another state.
If your state lets you keep part of the tax
Some states give a small discount for filing and paying on time. Texas, for example, allows a "0.5 percent timely filing discount" (Texas Comptroller).
The part you keep is income. The Schedule C instructions say that if the state or local government "allowed you to retain any part of the sales tax you collected, you must include that amount as income on line 6."
| Account | Debit | Credit |
|---|---|---|
| Sales Tax Payable | $760.00 | |
| Cash | $756.20 | |
| Other income: sales tax discount | $3.80 |
$760 × 0.5% = $3.80. Applying the rate to the tax due is our reading of the Texas rule.
Rules and rates vary by state, and some states have capped or ended their discounts. Our sales tax discounts by state table has each state's rule, cap and source for the 45 states with a sales tax and DC, and what a seller keeps on $5,000 of monthly tax. It's free to download as a CSV.
When the customer pays later
The month the tax is due can differ from the month the cash arrives. Texas is one state that spells it out. Retailers "may use a cash basis, an accrual basis, or any generally recognized accounting basis." Tax on a credit sale is reported "based upon the accounting method that the retailer uses for its regular books and records."
On accrual, the tax is due "in the reporting period in which the sale occurs"; on cash, "in the reporting period in which the payment is received" (34 Tex. Admin. Code §3.302). Other states set their own rules.
Say Harbor Coffee Co invoiced a $1,000 catering order on March 28 and was paid April 10. For a Texas retailer on accrual, the $80 of tax goes on the March return. On cash, it goes on the April return. The catering order is our illustration, not part of the March figures above.
When the books and the return use different methods, Sales Tax Payable won't tie in either month. Check which method the client reports on before you chase the difference.
Marketplace sales and Form 1099-K
When a marketplace collects the tax and sends it to the state, the tax isn't the seller's liability. So don't credit Sales Tax Payable for those orders.
Texas puts it this way: a marketplace seller is "not responsible for collecting and remitting sales and use tax on your sales through the marketplace if the marketplace provider has certified they are assuming these responsibilities."
The seller still needs its permit and still files its own returns. If the payout report shows the tax, record it in and out, or leave it out of both sides, so it nets to zero.
Don't copy a Form 1099-K total onto line 1 either. IRS Publication 334 says the form's amount "may include items that are not included in your receipts (such as sales tax)." Start from the books, and explain the difference in your workpapers.
Some books put the tax in sales and the payment in expenses
In an r/Bookkeeping thread we read, some commenters said they do this on purpose: collected tax goes to sales, and the payment to the state goes to an expense. The reason they give is that gross receipts in the books then match the Form 1099-K.
Profit comes out the same. Harbor Coffee Co's March would show $10,800 of sales, the $540 refund as a return, and a $760 tax expense. That's $9,500, the same as with Sales Tax Payable. But sales and expenses both carry the tax, and the balance sheet doesn't show the $760 owed until it's paid.
The tax return still needs the IRS treatment. For a tax imposed on the buyer, the Schedule C instructions say the amounts collected are "not included in gross receipts or sales nor are they a deductible expense."
So line 1 stays at $10,000, and the $760 isn't a line 23 deduction. Whoever prepares the return has to back both out. And Publication 334 already says a 1099-K can include sales tax (above).
If a client's books already work this way, we don't think they need rebuilding. Send the tax preparer the year's tax collected and paid, so both come out of the return.
For new books, we would use Sales Tax Payable: it keeps what the business owes on the balance sheet, and you can tie it to the return each month.
The costly version mixes the two. The tax goes to Sales Tax Payable, and the payment is also coded to an expense. That's the first row in the common mistakes: profit $760 too low.
How do you record sales tax you pay on purchases?
In short: Add it to the cost of whatever you bought. What the item is decides where the tax ends up and when it reaches profit.
“Treat any sales tax you pay on a service or on the purchase or use of property as part of the cost of the service or property.”
The same passage gives the three cases. A deductible expense takes its tax with it. Merchandise bought for resale includes the tax in its cost. For depreciable property, you "add the sales tax to the basis for depreciation."
The Schedule C instructions repeat it for line 23. Don't deduct sales tax on property bought for the business as a tax; instead, "treat these taxes as part of the cost of the property." Topic 703 on basis says the same: cost "includes sales tax and other expenses connected with the purchase."
So is sales tax capitalized or expensed? It follows the item. Tax on supplies or a service is expensed with them. Tax on equipment is capitalized with the equipment. Tax on inventory waits in inventory and reaches cost of goods sold as the goods sell.
| What you bought | Where the tax goes | Harbor Coffee Co, March |
|---|---|---|
| Supplies or a service | In the same expense account | $200 of cups and lids + $16 tax = $216 supplies expense |
| Inventory to resell | In inventory, then cost of goods sold as it sells | $1,000 of bagged coffee + $80 tax = $1,080 inventory |
| Equipment or another asset | In the asset's cost (basis), then depreciated | $2,400 espresso machine + $192 tax = $2,592 equipment |
Journal entries
| Account | Debit | Credit |
|---|---|---|
| Supplies expense | $216 | |
| Cash | $216 |
| Account | Debit | Credit |
|---|---|---|
| Equipment | $2,592 | |
| Cash | $2,592 |
IRS Publication 551 lists what the cost of property includes: "Sales tax. Freight. Installation and testing." So delivery and installation on the invoice go into the cost too. Depreciation, Section 179, or bonus depreciation is figured on the total.
Inventory: the tax reaches profit only as the goods sell
Merchandise for resale can be bought tax-free. The business gives the vendor a resale certificate, and the tax is charged later to the customer. If a vendor charges tax on inventory anyway, the tax sits in inventory with the goods. It isn't an expense in the month you paid it.
| Account | Debit | Credit |
|---|---|---|
| Inventory | $1,080 | |
| Cash | $1,080 |
| Cost of goods sold: $1,080 × 50% | $540 |
| Of which sales tax: $80 × 50% | $40 |
| Still in inventory at the end of March | $540 |
The other $40 of tax reaches profit when the rest sells. Better still, ask the vendor for a credit: with a resale certificate on file, the vendor shouldn't have charged it.
The $2,500 de minimis test
Under the de minimis safe harbor, a business without an applicable financial statement can elect to deduct tangible property instead of depreciating it. The limit is $2,500 per item or invoice (IRS Publication 334).
Does the tax count toward the limit? The regulations say to include "all additional costs (for example, delivery fees, installation services, or similar costs)" on the same invoice. They don't name sales tax.
But the IRS treats the tax as part of the item's cost, so we test the total with the tax. That's our careful reading, not an IRS example.
| Espresso machine: $2,400 + $192 tax | $2,592 |
| Over $2,500, so it's equipment on the balance sheet | Capitalize |
| Grinder (if bought instead): $2,300 + $184 tax | $2,484 |
| Under $2,500, so it can be expensed under the election | Part V |
Tested on the price alone, both look under the limit. With the tax, only the grinder is.
Two more conditions matter to a bookkeeper. First, the IRS says the safe harbor covers amounts "deducted by you for financial accounting purposes or in keeping your books and records." So the grinder has to be expensed in the books too, not capitalized there and deducted on the return.
Second, the election "does not include amounts paid for inventory." Ask the tax preparer whether the client makes the election before you choose the account.
Bookkeeper tip: Don't open a "Sales Tax Paid" or "Sales Tax Expense" account for purchases. QuickBooks Desktop's help page on vendor purchases describes one ("Track sales tax on purchases as an expense"), beside the option to track it as a liability. Such an account pulls the tax out of inventory and equipment, where the IRS says it belongs, and out of the de minimis test above.
What if the vendor didn't charge sales tax?
In short: Then, if the purchase is taxable, the business may owe use tax to its own state. In the books it works like sales tax you paid: part of the item's cost, with a payable until you file.
“Use tax is a nonrecurring tax that is complementary to sales tax and is imposed on the storage, use, or other consumption of tangible personal property or a taxable service in Texas.”
Use tax comes up when a seller, often one in another state or online, doesn't collect tax in the buyer's state. In Texas, permit holders report it as taxable purchases on their regular sales and use tax return. Check your state's return for the equivalent line.
For your books, the IRS wording already covers it ("the purchase or use of property").
| Account | Debit | Credit |
|---|---|---|
| Supplies expense | $540 | |
| Cash | $500 | |
| Use Tax Payable | $40 |
$500 × 8% = $40. When the return is filed: debit Use Tax Payable $40, credit cash $40. For inventory or equipment, debit that account instead of supplies.
In QuickBooks Desktop, a bill won't add the use tax for you. Intuit's help page says the program "is not designed to track sales tax automatically on non-sales transactions" such as bills and checks.
Its method for tax "to be paid later" matches the credit side of the entry above: an Other Current Liability account for the tax, paid later with a regular check. We haven't checked QuickBooks Online's own steps for use tax; the manual entry above works in any program.
Stock bought tax-free and then used in the business
No invoice shows the second case. A business takes something it bought for resale off the shelf and uses it, and the tax the resale certificate put off is now due. The Texas Comptroller says: "If you use the merchandise that you purchased by issuing a resale certificate, then you owe tax on the merchandise."
The tax is figured either on its fair market rental value for the period of use or on the purchase price. Other states have their own rules.
| Account | Debit | Credit |
|---|---|---|
| Supplies expense | $108 | |
| Inventory | $100 | |
| Use Tax Payable | $8 |
$100 purchase price × 8% = $8. The coffee leaves inventory at cost, and the use tax joins it in the expense.
So use tax is an expense only when the item is one. On supplies it joins supplies expense, on inventory it's part of inventory, and on equipment it's part of the basis.
When is sales tax the business's own expense?
In short: Only when the state imposes the tax on the seller, even if the seller passes it on to customers. Then what you charged goes into gross receipts, and the tax is a deduction on Schedule C line 23.
The rule that collected sales tax is never deductible holds only for a tax imposed on the buyer. The Schedule C instructions let you deduct "State and local sales taxes imposed on you as the seller" of goods or services.
They add: "If you collected this tax from the buyer, you must also include the amount collected in gross receipts or sales on line 1."
Publication 334 says the same in chapter 5, Items To Check. The IRS doesn't name the four taxes below. Applying its line to them is our reading of each state's own description.
| State | Tax | What the state says |
|---|---|---|
| Hawaii | General excise tax (GET) | "not a sales tax imposed when title passes. Rather, the general excise tax is a gross receipts tax" (Hawaii Administrative Rules §18-237-13-02.01) |
| New Mexico | Gross receipts tax (GRT) | "imposed on businesses, but it is common for a business to pass the GRT on to the purchaser" (New Mexico Taxation and Revenue Department) |
| Arizona | Transaction privilege tax (TPT) | "a tax on the vendor for the privilege of doing business in the state" (Arizona Department of Revenue) |
| Washington | Business and occupation (B&O) tax | "a tax on the seller and is a part of the seller's overhead. It is not a tax imposed on the buyer" (Washington Department of Revenue); Washington's retail sales tax is a separate tax, recorded as a normal liability |
The same month under a tax on the seller
Suppose Harbor Coffee Co were in a state that taxes the seller. Say it passed 8% on to customers, and the state return showed $800 owed. That last figure is our assumption: the state's own return decides what's owed, and it can differ from what you passed on.
| Harbor Coffee Co, March sales | Tax on the buyer (most states) | Tax on the seller |
|---|---|---|
| Cash from customers | $10,800 | $10,800 |
| Schedule C line 1, gross receipts | $10,000 | $10,800 |
| Schedule C line 23, taxes | $0 | $800 |
| Profit from these sales | $10,000 | $10,000 |
| Account for the tax | Sales Tax Payable (liability) | Taxes and licenses (expense), with a payable until you file |
| Account | Debit | Credit |
|---|---|---|
| Cash | $10,800 | |
| Sales revenue | $10,800 | |
| Taxes and licenses | $800 | |
| Gross receipts tax payable | $800 |
When you file: debit Gross receipts tax payable $800, credit cash $800. Washington businesses have both kinds: B&O tax is recorded this way, and retail sales tax is a normal liability.
For GAAP financial statements: ASC 606-10-32-2A lets a business elect to leave sales, use, and similar taxes collected from customers out of revenue. But "taxes assessed on an entity's total gross receipts" are outside that election (as quoted in Deloitte's Revenue Recognition Roadmap). If a client issues GAAP statements in one of these states, confirm the presentation with their CPA.
Other states word their rules in their own ways. Not sure who a tax is legally imposed on? Read the state revenue department's guidance before you choose a treatment.
Where does sales tax go on Schedule C?
In short: Each kind of sales tax lands in a different place on Schedule C, and sales tax collected from customers lands nowhere.
| Amount | Schedule C | Harbor Coffee Co, March |
|---|---|---|
| Sales, without collected tax imposed on the buyer | Line 1, gross receipts | $10,000 |
| Returns | Line 2 | $500 |
| Collected tax (on the buyer) and the payment to the state | Nowhere | $800 collected, $40 refunded, $760 paid |
| Discount the state let you keep | Line 6, other income | $3.80, if filed with the discount |
| Tax on supplies, and use tax on supplies | With the supplies, line 22 | In the $216, $540, and $108 |
| Tax on inventory | Cost of goods sold, Part III | $40 of the $540 sold in March |
| Tax on equipment | In depreciation or Section 179 (line 13, Form 4562) | In the $2,592 basis |
| Tax on an item under the de minimis limit | Part V, other expenses, if elected | The $2,484 grinder, if bought |
| Tax imposed on you as the seller | Line 1 (amount collected) and line 23 | Not in this example |
| Late-filing penalties | Not deductible |
Publication 334 lists "penalties and fines you pay to a governmental agency or instrumentality because you broke the law" among the expenses you can't deduct. So keep late-filing penalties in their own account, where they can't slip into taxes and licenses.
Not the same topic: this article covers sales tax in a business's books and on Schedule C. It doesn't cover personal itemized deductions on Schedule A. The tax on business purchases is already in the business costs above.
What are the common mistakes with sales tax in the books?
In short: Each one moves one figure by a fixed amount, so the amount tells you where to look. The table shows each mistake in the example coffee shop's March books, the safer entry, and the figure it moves.
Want a whole month of Harbor Coffee Co's books? Our simple journal entry examples have one, with payroll, a loan payment, the month-end adjustments, and a trial balance that ties.
✕ Payment coded as an expense
Profit is $760 too low, and Sales Tax Payable still shows $760 that was already paid.
✓ Payment applied to Sales Tax Payable
The liability goes to $0 and profit is right.
| Risky | Safer | What the mistake does |
|---|---|---|
| $760 payment to the state categorized as an expense, after the tax went to Sales Tax Payable | Debit Sales Tax Payable $760 | Profit $760 too low, and the payable still shows $760 that was paid |
| $1,080 card deposit booked as sales | $1,000 to sales, $80 to Sales Tax Payable | Revenue $80 too high, and the books $80 short of the return |
| $192 tax on the espresso machine booked to a "sales tax expense" account | Equipment at $2,592 | Basis $192 too low, and $192 deducted as a tax the IRS says belongs in the cost |
| De minimis tested on the $2,400 price, so the machine is expensed | Test $2,592 with the tax, and capitalize | $2,592 expensed instead of depreciated |
| $80 tax on inventory expensed when paid | Inventory at $1,080 | March cost $40 too high (half the coffee is still on the shelf) |
| No use tax on the $500 online order | Supplies $540, Use Tax Payable $40 | $40 owed to the state missing from the balance sheet |
| Line 1 copied from a Form 1099-K | Line 1 from the books: $10,000 | Gross receipts too high by any sales tax inside the 1099-K total |
| A tax on the seller treated like a buyer's sales tax | Line 1 $10,800, line 23 $800 | Gross receipts $800 too low; profit the same |
What if collected tax sat in sales for months?
In short: Move it out of sales month by month, then find out whether it was ever paid. Tax collected and never paid over is owed to the state, and that conversation needs the client's CPA.
The $80 tie-out above is one day's deposit. In a catch-up you may find months of it: every deposit booked to sales, tax and all. The fix is the same move, made month by month. Debit sales revenue and credit Sales Tax Payable for the tax inside each month's sales, and tie each month to its return.
Then check what happened to the money. If the returns were filed and paid, look for the payments; they may have been coded to an expense. A return the owner paid from a personal account won't show in the business bank at all. Debit Sales Tax Payable and credit Owner's Capital or a due-to-owner account; the owner draws guide sorts owner money by type. Recode them to Sales Tax Payable: each filed month should come back to zero, and anything left is the difference to explain.
If tax was collected but never paid over, it's the serious case: the money belonged to the state from the day it was collected (a former state auditor in one thread we read called it worse than never collecting).
Tax that was never charged at all is a different question, and whether the business owes it now depends on the state.
In both cases, bring in the client's CPA or an attorney before anyone contacts the state, and don't estimate penalties yourself. We haven't checked how paying uncollected back tax is treated for income tax; ask the CPA.
How do you tell the client? Describe the books, not whoever kept them. That was the advice in an r/Bookkeeping thread we read about telling an owner the books aren't ready:
Sample wording: tax found in sales
While catching up your books, I found that the sales tax your customers paid in [months] was recorded as sales. I've moved it to sales tax owed, month by month. Some of it doesn't match a filed return, so part of that tax may still be owed to the state. Before anyone contacts the state, I would like your CPA to go through the list with us. I'll send it to them this week.
How do you explain sales tax to a client?
In short: With the month's own numbers. The two sample replies below use the example coffee shop's March figures.
"Why does my P&L show $10,000 of sales when $10,800 hit the bank?"
Sample wording: sales vs. deposits
You're right that $10,800 came into the account in March. $800 of it was sales tax your customers paid on top of the $10,000 of sales. That $800 belonged to the state from the day you collected it. So it sits in Sales Tax Payable on the balance sheet, not in sales. After the $40 you refunded with a return, you owed $760, and that's what we paid with the March return. None of it is income or an expense for you.
"Why were the books $80 off the return?"
Sample wording: the monthly tie-out
Before we filed March, your books showed $680 of sales tax owed and the return showed $760. The $80 difference was one day's card deposit of $1,080 that was recorded entirely as sales, when $80 of it was tax. We've moved the $80 to sales tax owed, so March sales are $10,000, not $10,080, and the books now match the return.
Is the client asking about a Form 1099-K that shows more than the return? The same answer works: the total can include the tax your customers paid, which went to the state (above).
Frequently asked questions
Is sales tax an expense or a liability?
It depends on which side of the sale you're on. Sales tax you collect from customers is a liability: you hold it for the state until you file, so it goes to Sales Tax Payable, not to revenue or expenses. Sales tax you pay when you buy something for the business is part of that item's cost. So it ends up in the matching expense, in inventory, or in the asset's cost.
Should I record my sales tax payment to the state as an expense?
No, not for tax you collected from customers. The payment reduces Sales Tax Payable: debit Sales Tax Payable, credit cash. If the tax went to Sales Tax Payable, coding the payment as an expense makes profit too low and leaves the liability showing money you've already paid. The exception is a tax your state imposes on the seller, such as Hawaii's general excise tax, which is included in gross receipts and deducted as a tax.
Is sales tax collected considered income?
Not when the tax is imposed on the buyer, which is the usual case. IRS Publication 334 says state and local sales taxes imposed on the buyer that you were required to collect and pay over are not income. If your state lets you keep a small part of the tax as a timely-filing discount, the part you keep is income and goes on Schedule C line 6.
Do I include sales tax in gross receipts on Schedule C?
Leave it out when the tax is imposed on the buyer; it's neither gross receipts nor a deductible expense. The exception is a tax imposed on you as the seller. If you collected it from the buyer, include it in gross receipts on line 1 and deduct the tax on line 23 (Instructions for Schedule C).
Can you put sales tax as an expense?
Only the sales tax you pay on business purchases, and only as part of what you bought: tax on supplies goes in supplies expense, tax on inventory goes in inventory and then cost of goods sold, and tax on equipment goes into the equipment's cost. IRS Publication 334 says to treat sales tax you pay as part of the cost of the service or property, so don't open a separate sales tax expense account. Sales tax you collected from customers can't be an expense, because it was never your income; it's a liability until you pay the state.
Is sales tax on inventory part of cost of goods sold?
Yes. If you pay sales tax on merchandise you buy to resell, the tax is part of the cost of the merchandise. It becomes cost of goods sold when the goods sell. A business can avoid paying it in the first place by giving the vendor a resale certificate; Texas, for example, then charges the tax only if the business uses the goods itself.
Is sales tax capitalized or expensed?
It follows the item. Sales tax on equipment or another depreciable asset is capitalized: the IRS says to add the sales tax to the basis for depreciation, so a $2,400 espresso machine with $192 of tax goes on the books at $2,592. Sales tax on supplies or a service is expensed with them. Sales tax on inventory sits in inventory and becomes cost of goods sold as the goods sell. An item under the $2,500 de minimis limit can be expensed under the election, and the tax counts toward that limit in our reading.
Does sales tax count toward the $2,500 de minimis limit?
The IRS doesn't say so in those words. But the tax is part of the item's cost, and the de minimis rule requires you to include other costs on the same invoice, such as delivery and installation. The careful approach is to test the total including tax: a $2,400 item with $192 of tax is $2,592, which is over $2,500. That is our careful reading, not an IRS example, so ask the tax preparer about items close to the limit. The safe harbor also applies only if the books expense the item too.
What is use tax, and do I owe it on online purchases?
Use tax is the buyer's side of sales tax. If you buy something taxable for the business and the seller doesn't charge sales tax, for example an out-of-state online seller, you may owe use tax to your state. In Texas it's reported as taxable purchases on the regular sales and use tax return; other states have their own line. The same can apply when the business uses stock it bought tax-free for resale. For your books it works like sales tax you paid: it's part of the cost of the item.
Does Form 1099-K include sales tax?
It can. IRS Publication 334 says the amount on a Form 1099-K may not be the amount to report as income. It may include items that are not included in your receipts, such as sales tax. Report gross receipts from the books, without collected tax imposed on the buyer, and keep a note of how the 1099-K total ties to them.
Is tax considered an expense for a business?
Some taxes are deductible business expenses and some aren't; sales tax you collect is neither, because it isn't yours. IRS Publication 334 lets a business deduct taxes directly attributable to it, such as real estate tax on business property and the Social Security, Medicare and FUTA taxes it pays as an employer, but not federal income tax. Sales tax you pay on purchases is part of what you bought.
Are sales tax penalties deductible?
No. IRS Publication 334 lists penalties and fines paid to a government agency because you broke the law among the expenses you can't deduct. Record late-filing penalties in their own account, not in Sales Tax Payable or in a general tax expense account, so you can leave them out at tax time.
How we built this page
Ledgental Team wrote this article and drew the diagrams. Ledgental also makes a bookkeeping app that's free during its beta and free tools for bookkeepers; this article doesn't sell either one. The companion sales tax reconciliation tool rolls Sales Tax Payable forward with the same logic.
What the rules rest on
- The federal treatment comes from IRS Publication 334 and the Schedule C instructions, quoted word for word where they settle the point: tax collected and paid over is neither income nor expense; tax paid on a purchase is part of its cost; tax that is legally on the seller goes in gross receipts and is deducted on line 23.
- The de minimis safe harbor ($2,500 per item or invoice, with the book-conformity condition and the exclusion of inventory) comes from the IRS tangible property regulations pages linked in the sources.
- State points (seller-imposed taxes in Hawaii, New Mexico, Arizona, and Washington; use tax on stock taken from tax-free inventory; marketplace sales) come from each state's revenue department, listed in the sources. State rules change often, and this article doesn't cover rates or filing.
- The QuickBooks steps are quoted from Intuit's own help pages (linked in the sources), read on October 11, 2026; menus change, so check the page if a step looks different.
- Practitioner habits (collected tax booked in sales; telling a client about tax found later) come from r/Bookkeeping threads we read; they show what some people do, not a rule.
- The example (Harbor Coffee Co, Jordan Miles, Northline Bookkeeping) is fictional, 8% is an example rate, and the amount owed in the tax-on-the-seller example is our assumption. Every journal entry uses the same numbers, so they can be checked against each other.
What changed
- October 12, 2026: rewritten in shorter sentences and paragraphs, and each section's "In short" lead now gives the answer first. New: books that put collected tax in sales and the payment in expenses, a practice described in an r/Bookkeeping thread, with what the return still needs. New section on tax found in sales months later or never paid over, with wording for the client. Also added QuickBooks Desktop's liability method for use tax, and the Texas discount arithmetic is labeled as our reading. Later the same day: the decision tree tags each answer in words (Owed, Income or cost, Not yours) instead of leaving it to color, and its number badges and arrow label are larger; a link opens our reconciliation tool with Harbor Coffee Co's March numbers filled in; the discount paragraph links our state-by-state discount table; and the FAQ on whether tax is an expense now opens with the answer.
- October 11, 2026: added a screenshot of our reconciliation tool showing the $80 tie-out, the QuickBooks Online steps for the payment and an adjustment, a tip on QuickBooks Desktop's "sales tax on purchases as an expense" option (both read at Intuit's help pages), and a note on "capitalized or expensed." Three FAQs were rewritten to match searched questions: "Can you put sales tax as an expense?", "Is sales tax capitalized or expensed?" and "Is tax considered an expense for a business?" IRS and Texas quotes re-read.
- October 4, 2026: added this "How we built this page" section, a citation box and the reuse license (CC BY 4.0), and a link icon beside every heading.
- September 30, 2026: rewritten with question headings and "In short" leads, six jump cards, ten journal entries (was seven), worked examples (the $80 tie-out, inventory half sold, the de minimis test at $2,592 against $2,484), comparison tables and twelve FAQs; IRS and Texas sources re-checked.
- September 2026: first published.
Cite this page
Copy one of these lines to credit the page. To link to one section, use the link icon beside its heading.
- Plain line
- Ledgental, Is Sales Tax an Expense?, updated October 2026, https://ledgental.com/blog/is-sales-tax-an-expense
- APA
- Ledgental. (2026, October). Is Sales Tax an Expense?. https://ledgental.com/blog/is-sales-tax-an-expense
- Chicago
- Ledgental. “Is Sales Tax an Expense?.” Last modified October 2026. https://ledgental.com/blog/is-sales-tax-an-expense.
Reusing this page: the article's text, tables, and diagrams are licensed under CC BY 4.0. Credit "Ledgental" with a link to this page. Quotations from the IRS and state agencies are public domain, and quotations from other sources stay under their owners' terms.
Sources
- Publication 334 (2025), Tax Guide for Small Business, Internal Revenue Service
- Instructions for Schedule C (Form 1040) (2025), Internal Revenue Service
- Publication 551 (12/2025), Basis of Assets, Internal Revenue Service
- Topic no. 703, Basis of assets, Internal Revenue Service
- Tangible property final regulations (de minimis safe harbor), Internal Revenue Service
- 26 CFR 1.263(a)-1(f), de minimis safe harbor, Electronic Code of Federal Regulations
- Use tax, Texas Comptroller of Public Accounts
- Sales and use tax FAQs: resale certificates, Texas Comptroller of Public Accounts
- Marketplace providers and sellers, Texas Comptroller of Public Accounts
- Sales and use tax FAQs: reporting and paying, Texas Comptroller of Public Accounts
- 34 Tex. Admin. Code §3.302, accounting methods and credit sales, Legal Information Institute, Cornell Law School
- Hawaii Administrative Rules §18-237-13-02.01, Justia Regulations
- Gross receipts overview, New Mexico Taxation and Revenue Department
- Transaction privilege tax (TPT) forms, Arizona Department of Revenue
- Business and occupation tax, Washington Department of Revenue
- ASC 606-10-32-2A, sales taxes and similar taxes (Revenue Recognition Roadmap, 6.7), Deloitte DART
- Manage sales tax payments in QuickBooks Online (updated September 2026), Intuit QuickBooks help
- Track sales tax on purchases from vendors (QuickBooks Desktop, updated August 2026), Intuit QuickBooks help
General information about US federal rules and general bookkeeping practice, not tax or legal advice. Rules and quotes were checked at the IRS and the state revenue departments listed above in September and October 2026, and the QuickBooks steps at Intuit's help pages in October 2026; state sales tax rules, rates, and discounts change often. Harbor Coffee Co, Jordan Miles, and Northline Bookkeeping are fictional, 8% is an example rate, and the amount owed in the tax-on-the-seller example is our assumption. Confirm the treatment for a specific client with their tax preparer. This page isn't affiliated with the IRS or any state agency.